For years, private equity investors relied almost exclusively on successful exits to lock in their gains. But as anyone in the private equity space soon finds out, IPOs can stall, dealmaking can slow down, and buyers can become more cautious due to industry or broader macroeconomic concerns.
This has tied up capital longer than expected, complicating liquidity planning and portfolio rebalancing for limited partners. Even general partners have had to deal with delayed distributions and the resulting stall in fresh capital.
In recent years, private investors have turned to the private equity secondary market to lock in gains before a traditional exit. This has helped to minimise the illiquidity challenge of private equity investing.
But the private equity secondary market can be tricky, especially on pricing. Institutional investors (endowments, insurance companies, pension funds, family offices, among others) must approach it cautiously, balancing the desire for liquidity with concerns about other risks.
In what follows, we will examine the rise of the private equity secondary market and how private equity investors should approach it. We’ll cover:
- Why are private equity investors turning to secondaries market?
- Current trends defining the private equity secondary market
- Navigating the dynamics of the private equity secondary market
Do you want to learn more about private markets and the opportunities they present? Sign up today for the cio investment club’s newsletter.
1. Why are private equity investors turning to secondaries market?
The secondaries market, led by the private equity secondary market, has grown remarkably in recent years.
“Transaction activity in the secondaries market is pacing for a third consecutive annual record,” according to S&P Global in a September 2026 report.
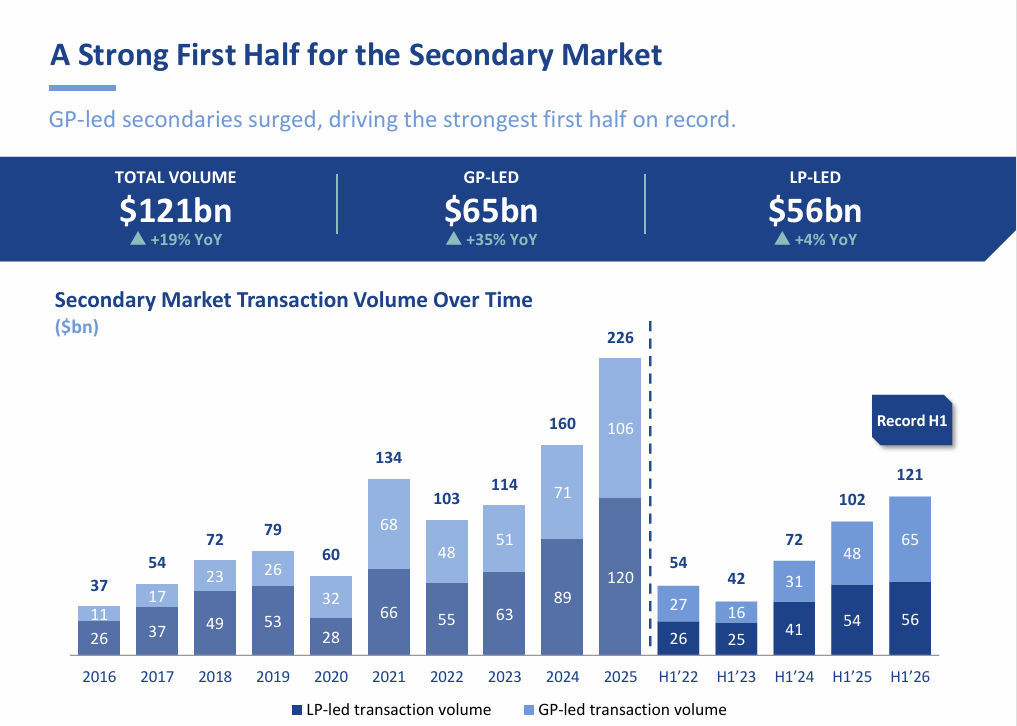
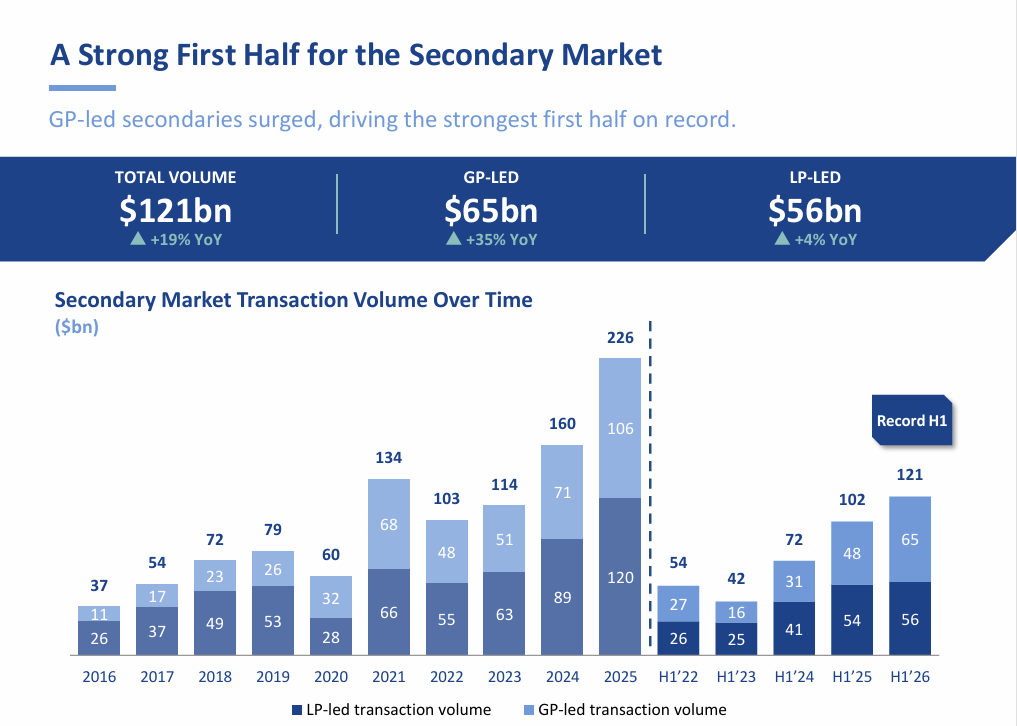
In the first half of 2026, transaction volume in secondaries market exceeded $120 billion, according to data from Evercore, an investment bank. This is a 20% year-on-year growth and the strongest first-half result on record.
Transaction Volume in Secondaries Market
Source: Evercore
More importantly, transaction volume grew by 510.8% from 2016 to 2025, a remarkable 22.3% compounded annual growth rate (CAGR).
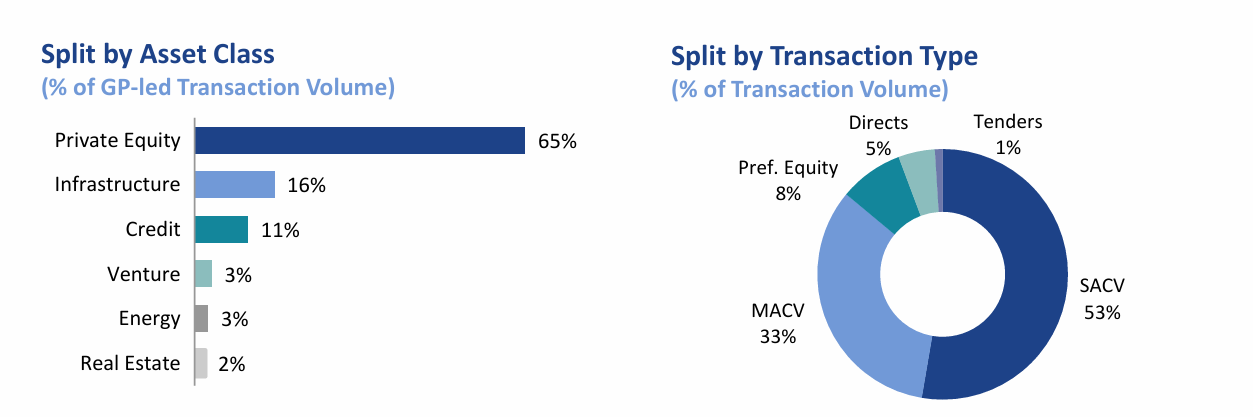
About 65% of GP-led transactions are in private equity, as seen below:
Split of GP-Led Transactions By Asset Type
Source: Evercore
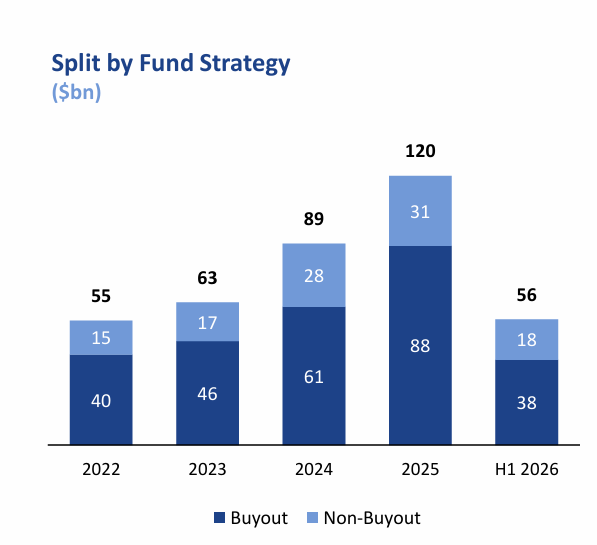
Similarly, 68% (38/56) of LP-led transactions are in private equity buyout funds (where private equity firms acquire controlling stakes in companies and work to grow, restructure, and sell them eventually). Non-buyout funds (real estate funds, infrastructure funds, venture capital funds, growth equity funds, private credit funds, etc.), though growing, continue to trail.
Split of LP-Led Deals By Fund Strategy
Source: Evercore
In other words, the private equity secondary market continue to dominate the growth in secondaries market.
But which factors are driving this growth?
Below are the most relevant ones:
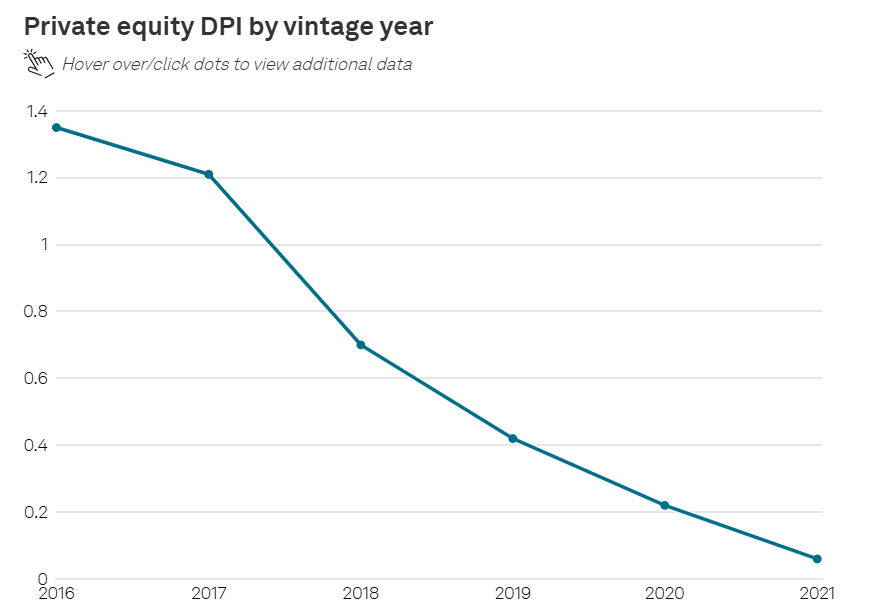
- Challenging exit environment: Private equity investors have struggled to exit their investments through standard channels. S&P Global noted that since 2018, the median distribution-to-paid-in-capital (DPI) ratio for PE investments has remained below 1X.
Private Equity DPI By Vintage Year
Source: S&P Global
“Exits and distributions have slowed, so capital is stuck,” according to Keith Sant, founder of Kind House Buyers, a residential and CRE investment firm. “Secondaries let investors raise liquidity and rebalance without waiting on a fund’s natural life cycle.”
- Interest of GPs in the secondary market: Limited partnership (LP)-led deals took centre stage in the first wave of interest in secondary transactions. This makes sense, since liquidity was the main driver.
However, as holding periods have extended and capital has become more available, general partners (GPs) have increased their participation in the secondary market, according to Wellington Management, an investment management firm.
As the chart below shows, GP-led deals have steadily increased, even outpacing LP-led deals in the first half of 2026.
Transaction Volume in Secondaries Market
Source: Evercore
The most common GP-led deals are continuation vehicles, which GPs use to extend the holding periods of private equity funds that have reached the end of their lives.
- Portfolio rebalancing needs: Even without urgent liquidity needs, LPs use the secondary market to diversify their portfolios across investment strategies, geographies, and vintage years, according to Carta, a financial software company.
In fact, the secondary market's next growth phase will be driven by investors embracing it as an active portfolio management tool, according to Bruno Bertrand-Delfau, a partner at Proskauer, a law firm, in an interview with S&P Global.
- Exploring investment opportunities: Some institutional investors also see the secondary market as an opportunity to purchase quality assets at a discount to net asset value (NAV).
This is often a good approach when an investor is unsure of a primary investment. Instead of buying from the fear of missing out (FOMO), they can wait for another opportunity in the secondary market.
- J-curve mitigation: During the early years of private equity investments, returns are often negative. Returns improve as investments mature and investors exit.
One of the key differences between primary and secondary investment in private equity is that the latter mitigates the J-curve. Investors can enter when the asset has moved past its low-return stage. Thus, they can ride the higher-return phase without enduring the low-return phase.
- Reduced blind pool risk: The underlying assets in investment portfolios for sale in the secondaries market are often known, reducing blind pool risk (the bane of primary funds).
As we will see, single-asset continuation vehicles are the most popular GP-led deals, and they focus on single assets that are easier to analyse.
- Technological advancement: Carta also notes that digital platforms and sophisticated data analytics tools have made it easier for LPs and GPs to conduct due diligence and connect with potential buyers.
2. Current trends defining the private equity secondary market
Certain trends currently define the private equity secondary market. Understanding these will help institutional investors focus their attention on where growth is palpable and adjust their strategies to reflect what is currently obtainable.
We review some of these trends below:
Continuation vehicles dominate GP-led transactions
GPs use continuation vehicles to extend the holding period of well-performing portfolio companies.
Existing LPs can roll their investment into the continuation fund or sell their interest to secondary buyers. Continuation funds also offer new buyers opportunities to invest in proven PE assets.
Continuation vehicles are growing because they meet the needs of all investor types. GPs get more time to grow the asset, LPs can access liquidity, and new buyers can hop in.
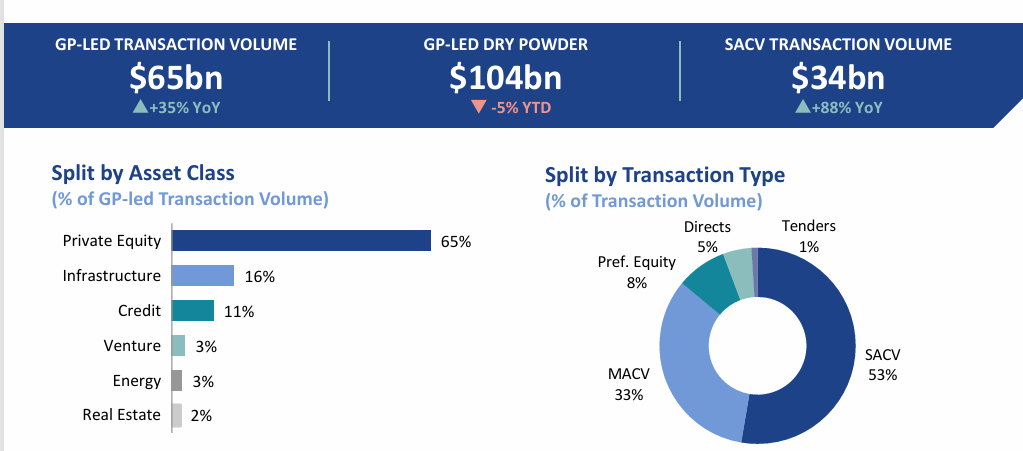
As shown below, continuation vehicles (single-asset and multi-asset) account for 86% of all GP-led secondary market transactions.
Overview of GP-Led Secondary Transactions
Source: Evercore
Single-asset continuation vehicles are more popular than multi-asset continuation vehicles
While CVs dominate overall, single-asset variants are the most popular.
“SACVs now account for 53% of the GP-led market, totalling approximately $34bn of volume, as sponsors back their highest-conviction single companies,” noted Evercore.
In other words, GPs are more likely to extend the holding period of particular assets rather than the entire fund.
“The large amount of locked-up capital and the growth of continuation vehicles remain tailwinds for the private equity secondary market,” Sant added.
SACVs are moving beyond technology
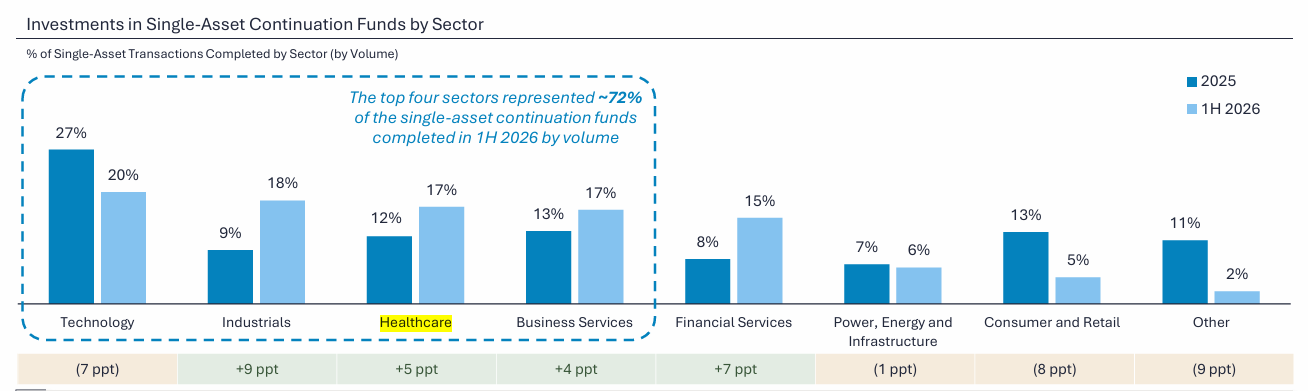
The share of technology in SACVs declined from 27% in 2025 to 20% in H1 2026, according to Lazard, an asset management firm.
In contrast, interest is growing in industrials, healthcare, business services, and financial services, as seen below.
Investments in Single-Asset Continuation Funds By Sector
Source: Lazard
Falling interest in technology reflects greater scrutiny of software and SaaS assets due to the AI disruption, according to Lazard.
In contrast, industrials are growing as buyers favor businesses with resilient end markets and recurring revenue. Healthcare and business services also benefit from interest in defensibility and a long-term contracted revenue base, respectively.
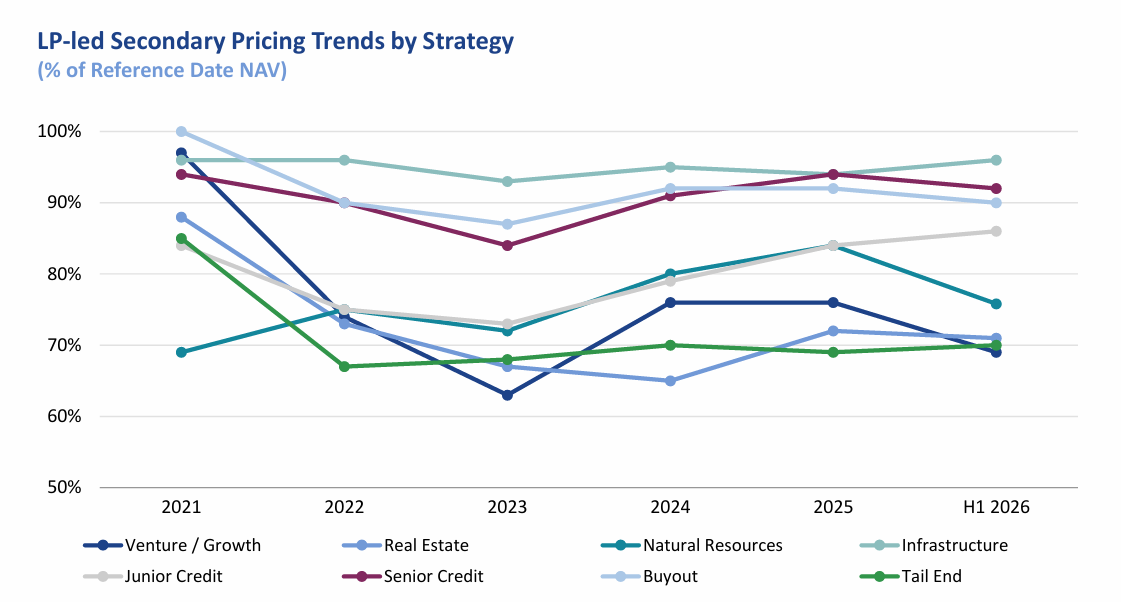
Pricing dynamics differ in LP-led and GP-led deals
As seen below, LP-led deals in the PE secondary market (and other LP-led secondaries) are unlikely to exceed the NAV:
LP-led Secondary Pricing Trends
Source: Evercore
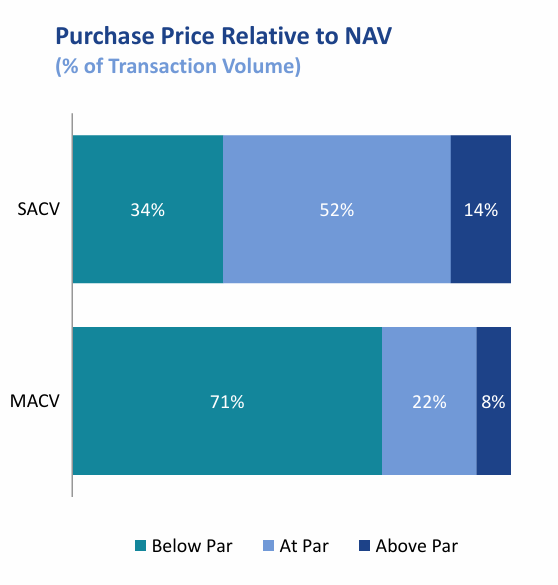
In contrast, GP-led deals, especially SAVCs, tend to get closer to the NAV or even exceed it.
Purchase Price Relative to NAV in GP-Led Deals
Source: Evercore
This makes sense because SAVCs hold quality assets GPs want. Secondary buyers are more likely to pay a premium for such assets.
Secondaries are supporting private equity fundraising
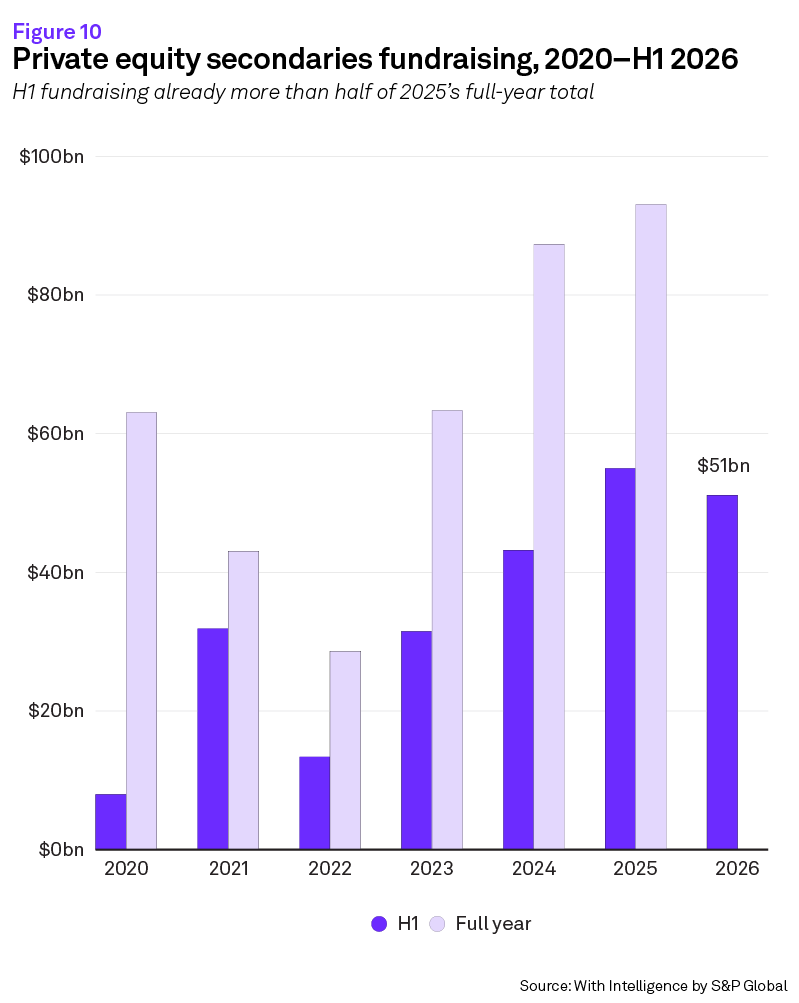
In H1 2026, the PE secondary market raised $51 billion, according to With Intelligence, the alternative investment intelligence arm of S&P Global. If current trends persist, fundraising will exceed $100 billion by year-end, a historic record.
Private Equity Secondaries Fundraising
Source: With Intelligence
Retail capital is showing interest in the private equity secondary market
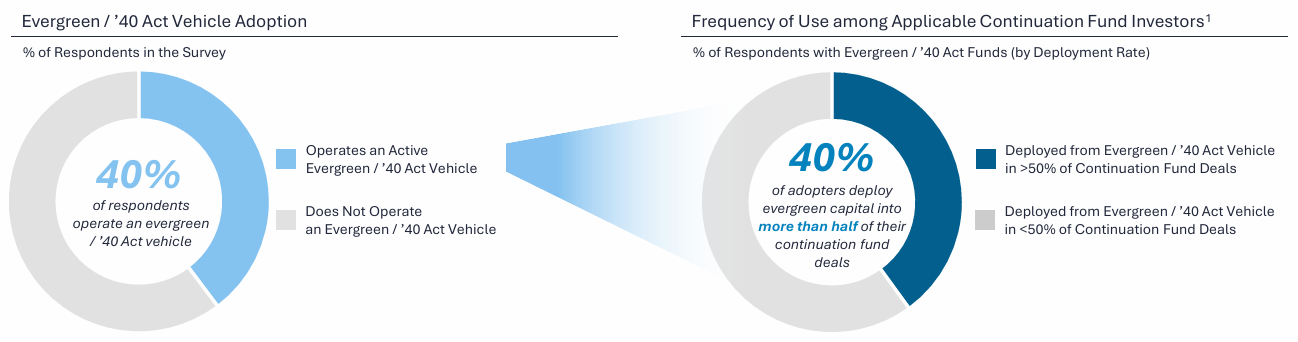
Private wealth capital has been adding liquidity to the private equity secondary market.
As this chart shows, 40% of respondents deploy evergreen capital into more than half of their continuation fund deals.
Use of Evergeen/ ‘40 Act Vehicles in Continuation Fund Deals
Source: Lazard
3. Navigating the dynamics of the private equity secondary market
Given the trends we have identified, institutional investors must embrace a strategic approach to the PE secondary market.
What does that look like?
Evaluating CV deals carefully
As GP-led transactions become more popular, it is crucial to learn to evaluate their underlying value.
Many GP-led deals trade at prices close to, or even above, NAV. Asset managers should conduct detailed analysis to ensure valuations are fair. If a secondary-market asset sells above NAV, the GP should explain why the asset quality warrants that valuation.
Other factors to consider when evaluating a GP-led deal include potential conflict of interest (principal and agent), future growth opportunities, why the GP is extending ownership, and alignment with long-term investment policy statements.
Evaluate LP deals carefully
Asset managers also buy the remaining unfunded commitments of private-equity investments.
This makes it important to consider the quality of the underlying portfolio companies, the GP’s track record, expected holding period, exit opportunities, and cash flow projections to determine if the deal is worth it.
Identify value opportunities
Many LP-led deals trade at a discount to NAV. But that alone does not indicate value.
Asset managers must ensure the asset's intrinsic value truly exceeds its secondary-market price, irrespective of the spread on its NAV. In other words, asset managers should prefer a high-quality asset selling at a 1% discount over a mid-quality asset selling at a 5% discount.
When LPs face cash-flow crunches, asset managers should stay alert for value opportunities. They should also consider quality tail-end portfolios, which are likely to sell at attractive discounts.
Design a diversified portfolio
Asset managers should build a portfolio diversified across:
- Fund vintages: Combining older and newer fund vintages can help smooth out cash flows (some are in the investment phase while some are in the harvesting phase), diversify across macroeconomic cycles (some benefit from growth years and some from contraction years), and manage the J-curve (immediate gains of older funds offset the losses of new funds).
- Sectors: As we have seen, AI disruption is leading investors to diversify away from software. A diversified portfolio can help to profit from opportunities across various sectors.
- Geographic regions: North America and Europe, the Middle East, and Africa (EMEA) continue to dominate both GP-led and LP-led transactions. The Asia Pacific (APAC) and the rest of the world (ROW) remain largely untapped.
For now, asset managers should look beyond North America by diversifying across EMEA, and keep an eye on APAC.
- General partners: The performance gap among GPs tends to widen in private markets. Diversifying across GPs helps eliminate selection risk and capture the operational strengths of multiple GPs.
Be realistic about liquidity expectations
Secondaries markets don’t make private markets public.
Asset managers should expect negotiated pricing, legal documentation, extensive due diligence, transfer approvals, and a long closing period.
Setting the right expectations can help with investment planning.
Build relationships with secondary managers
Although they improve liquidity, secondary transactions remain private. Many of the attractive opportunities may not be broadly marketed.
Asset managers with strong professional relationships with secondary fund managers, GPs, placement agents, and even investment banks can access opportunities they wouldn’t otherwise.
Interacting with other asset managers is one way you can better position yourself to identify profitable opportunities.
At cio investment club, we connect you with other asset managers and professional investors navigating global financial markets. We also organise exclusive roundtables and investment breakfasts where you can network with other experts and explore opportunities.
Do you want to become a part of an investing community that helps you identify opportunities in private markets? Register today to join the cio investment club.
Takeaways
- Slower exits and extended holding periods are pushing LPs and GPs to use secondary transactions to unlock capital and manage portfolios.
- PE secondary transaction volume exceeded $120 billion in the first half of 2026, up 20% year over year, according to Evercore.
- Continuation vehicles are reshaping GP-led deals by letting GPs retain high-conviction assets while giving existing LPs liquidity and new investors an entry point.
- Institutional investors need to assess underlying asset quality, valuations, conflicts of interest, diversification, and liquidity expectations before committing capital.
This document is produced by Instaconnect Limited, trading as cio investment club, a company registered in England & Wales with registration number 15262951.
Instaconnect Limited is neither authorised nor regulated by the Financial Conduct Authority in the United Kingdom nor the Securities and Exchange Commission in the United States of America.
This document is a marketing documentation and is not intended to constitute an invitation or an inducement to engage in any investment activity. It is not intended to constitute investment advice and should not be relied upon as such. It is not intended and none of Instaconnect Limited, its holding companies or any of its or their associates, or any of the participants in the documentation, shall have any liability whatsoever for (a) investment advice; (b) a recommendation to enter into any transaction or strategy; (c) advice that a transaction or strategy is suitable or appropriate; (d) the primary basis for any investment decision; (e) a representation, warranty, guarantee with respect to the legal, accounting, tax or other implications of any transaction or strategy; or (f) to cause Instaconnect Limited to be an advisor or fiduciary of any recipient of this report or other third party.
The content and graphical illustrations contained in this document are provided for information purposes and should not be relied upon to form any investment decisions or to predict future performance. Instaconnect Limited recommends that recipients seek appropriate professional advice before making any investment decision. Although the information expressed is provided in good faith, Instaconnect Limited does not represent, warrant or guarantee that such information is accurate, complete or appropriate for your purposes and none of them shall be responsible for or have any liability to you for losses or damages (whether consequential, incidental or otherwise) arising in any way for errors or omissions in, or the use of or reliance upon the information contained in this document.
To the greatest extent permitted by law, we exclude all conditions and warranties that might otherwise be implied by law with respect to the document, whether by operation of law, statute or otherwise, including as to their accuracy, completeness, or fitness for purpose.
Instaconnect Limited and its logo are proprietary trademarks of Instaconnect Limited and are registered in the United Kingdom. Unauthorised copying of this document is prohibited.
© Copyright Instaconnect Limited 2026